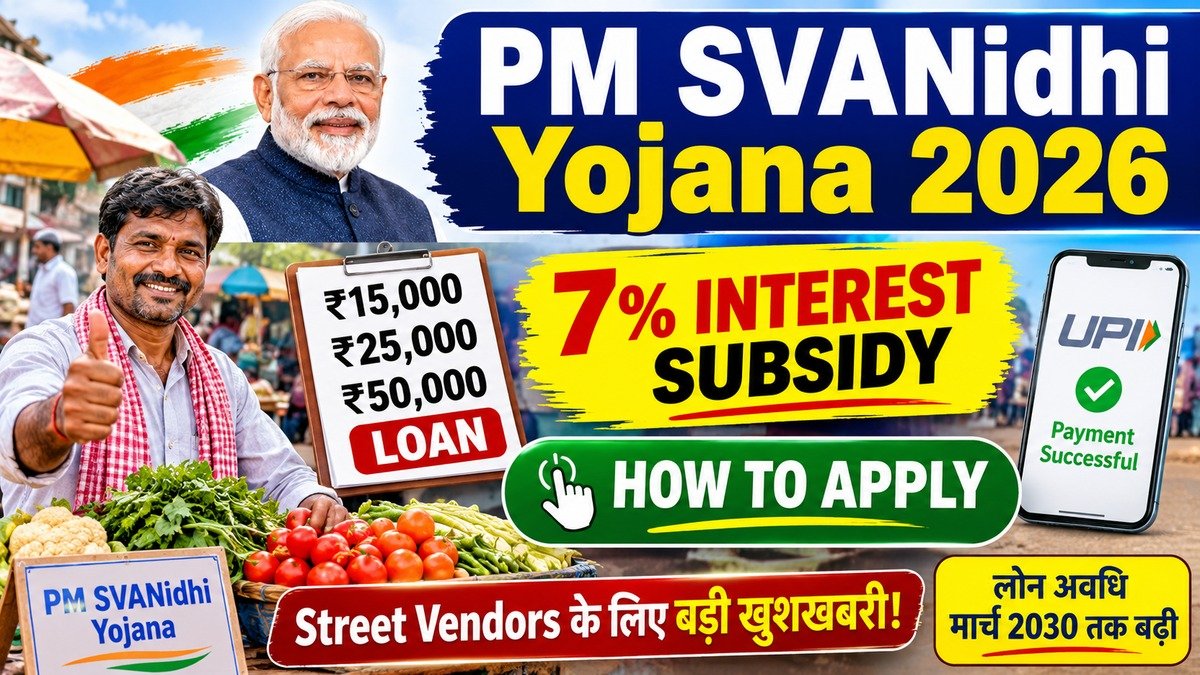
Check PM SVANidhi Yojana 2026 loan amounts up to ₹50,000, 7% interest subsidy, digital cashback, eligibility, and online application steps.
Operating a small street vending business requires daily working capital to buy fresh stock, pay suppliers, and manage immediate cash flow needs. If you are a roadside vendor who has had to rely on local moneylenders charging exorbitant daily interest rates just to keep your cart running, financial stress can feel relentless.
Fortunately, the Prime Minister Street Vendor’s AtmaNirbhar Nidhi (PM SVANidhi) scheme provides collateral-free working capital loans specifically tailored to help street vendors rebuild and expand their livelihoods.
What is PM SVANidhi Yojana and Who Launched It?
Launched by the Ministry of Housing and Urban Affairs, Government of India, in June 2020, PM SVANidhi is a special micro-credit facility designed to empower street vendors affected by economic disruptions.
The scheme provides affordable working capital loans in progressive tranches, encourages digital transactions through attractive cashback incentives, and rewards timely repayments with higher credit limits.
Key Benefits of the Scheme
- Progressive Loan Tranches: Access working capital loans up to ₹15,000 in the first tranche, ₹25,000 in the second, and up to ₹50,000 in the third tranche.
- Collateral-Free Credit: Zero security or collateral required to secure the loan from participating banks or microfinance institutions.
- Interest Subsidy: An interest subsidy of 7% per annum is credited directly to eligible borrowers upon timely repayment.
- Digital Incentives: Earn cashback rewards on digital UPI transactions and gain eligibility for UPI-linked RuPay credit cards.
Eligibility Criteria
To qualify for a PM SVANidhi loan, applicants must fulfill these core conditions:
- Must be a street vendor operating in urban or peri-urban vending zones.
- Must possess a Certificate of Vending (CoV) or Identity Card issued by Urban Local Bodies (ULBs).
- Vendors without formal IDs who have been surveyed can also apply using a Letter of Recommendation (LoR) issued by the ULB or Town Vending Committee (TVC).
Documents Required
Keep these documents handy before submitting your application:
- Aadhaar Card (mandatory for identity verification in most states)
- Voter ID, Driving License, or MNREGA Card
- Certificate of Vending or Letter of Recommendation (LoR)
- Active bank account passbook linked with Aadhaar
How to Apply Online for PM SVANidhi Loan (Step-by-Step)
If you want to apply for working capital support, follow these simple steps:
- Visit the official JanSamarth or PM SVANidhi portal at pmsvanidhi.mohua.gov.in.
- Click on the loan application link corresponding to your required tranche amount.
- Authenticate your identity using your mobile number and Aadhaar details.
- Upload your Certificate of Vending, LoR, and bank details.
- Submit your application; once processed and approved by the lending institution, funds are disbursed directly into your bank account.
Common Mistakes and Things to Watch Out For
- Missing Repayment Schedules: Failing to pay monthly EMIs on time makes you lose the 7% interest subsidy and blocks your eligibility for higher loan tranches.
- Incorrect Vending Documentation: Ensure your Letter of Recommendation or Certificate of Vending matches your current operating location correctly.
- Unauthorized Agents: Do not pay fees to intermediaries; PM SVANidhi loan applications are processed transparently through official banking channels.
Frequently Asked Questions (FAQs)
1. What is the repayment tenure for PM SVANidhi loans?The repayment period is structured as 12 months for the first tranche, 18 months for the second tranche, and up to 36 months for the third tranche.
2. Do I need to pledge collateral to get this loan?No, loans under this scheme are completely collateral-free.
3. How do I get the 7% interest subsidy? The interest subsidy is calculated on a yearly basis and credited directly to your bank account upon making timely installment repayments.
4. Can I get a higher loan amount after repaying the first loan? Yes, successful repayment of the first loan makes you eligible for a higher limit of ₹25,000, followed by ₹50,000 in the third tranche.
5. What digital rewards does the scheme offer? Vendors receive cashback incentives for undertaking regular digital UPI transactions and can qualify for a RuPay Credit Card.
Conclusion
The PM SVANidhi Yojana gives street vendors the financial boost needed to stabilize and expand daily trade operations. Visit pmsvanidhi.mohua.gov.in today to check your eligibility and apply for your working capital loan in 2026.